
Since April 2026, Main Street Capital has been in a holding pattern, posting a small return of 2.4% while floating around $55.26. The stock also fell short of the S&P 500’s 17.5% gain during that period.
Is there a buying opportunity in Main Street Capital, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Main Street Capital Not Exciting?
We’re sitting this one out for now. Here are three reasons why there are better opportunities than MAIN, plus one stock we’d rather own.
1. Lackluster Revenue Growth
Long-term growth is the most important, but within financials, a stretched historical view may miss recent interest rate changes and market returns. Main Street Capital’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 5.5% over the last two years was well below its five-year trend. 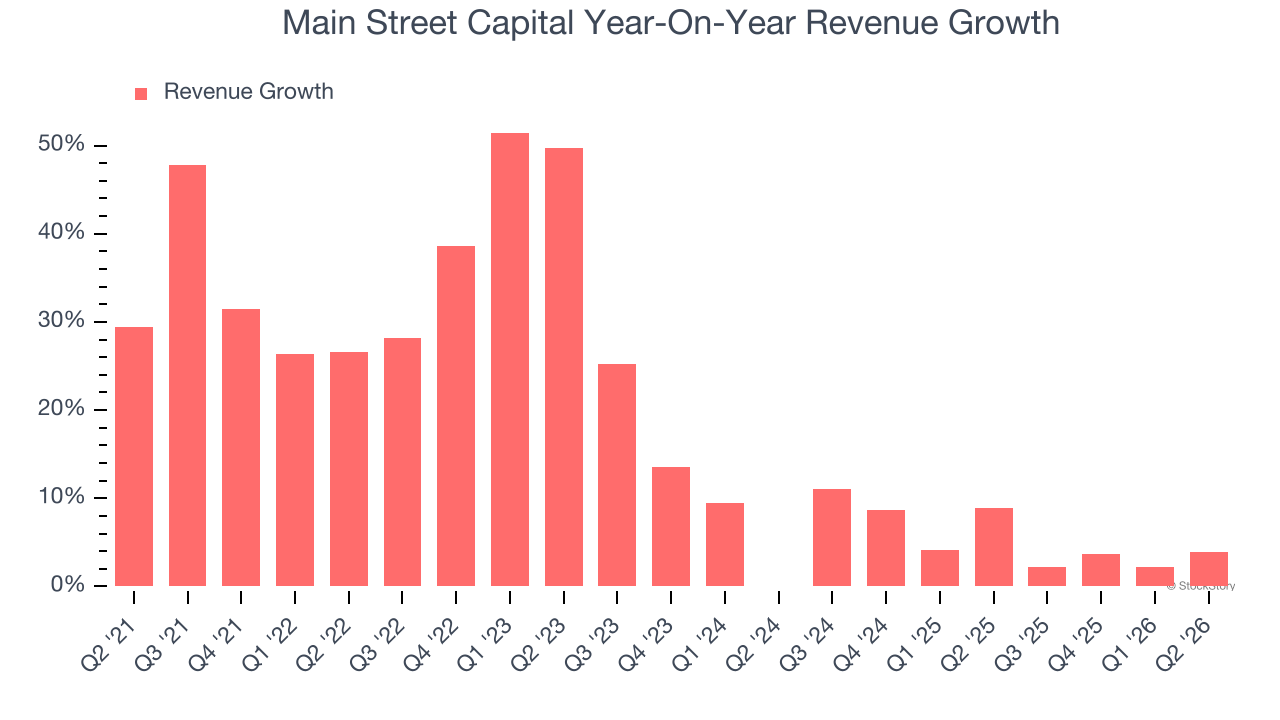 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
2. EPS Took a Dip Over the Last Two Years
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
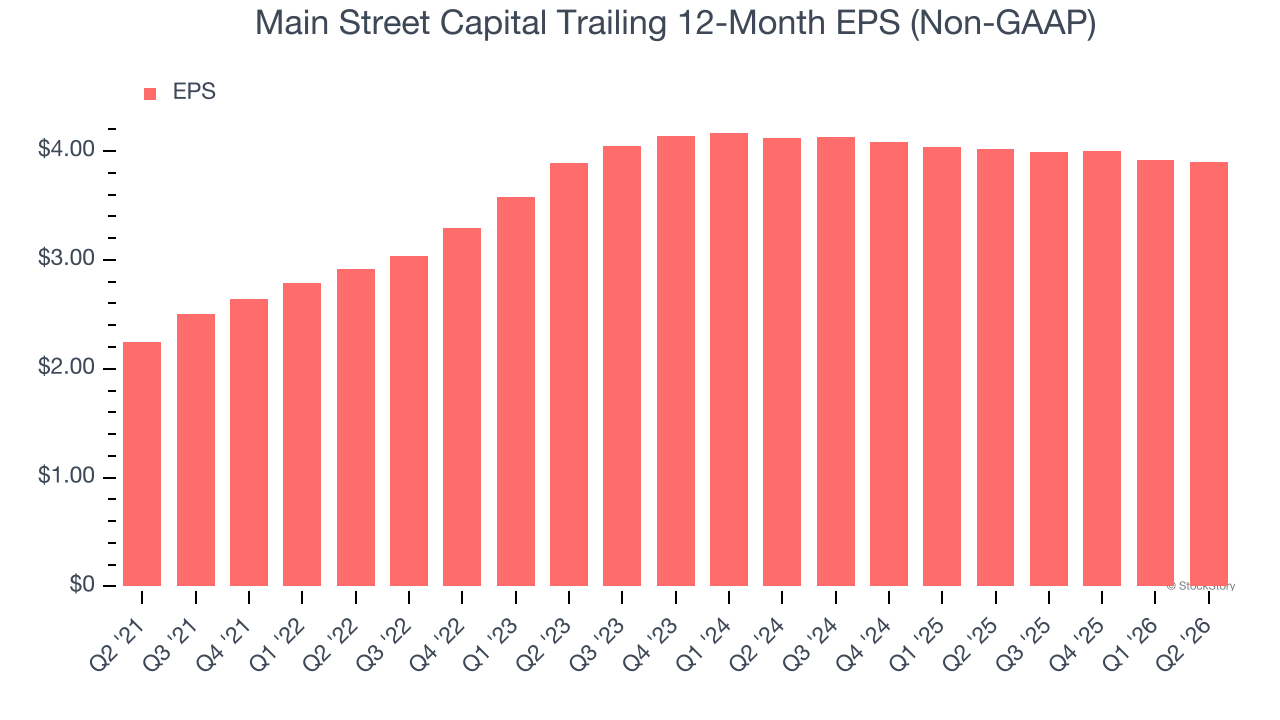
Sadly for Main Street Capital, its EPS declined by 2.7% annually over the last two years while its revenue grew by 5.5%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Substandard TBVPS Growth Indicates Limited Asset Expansion
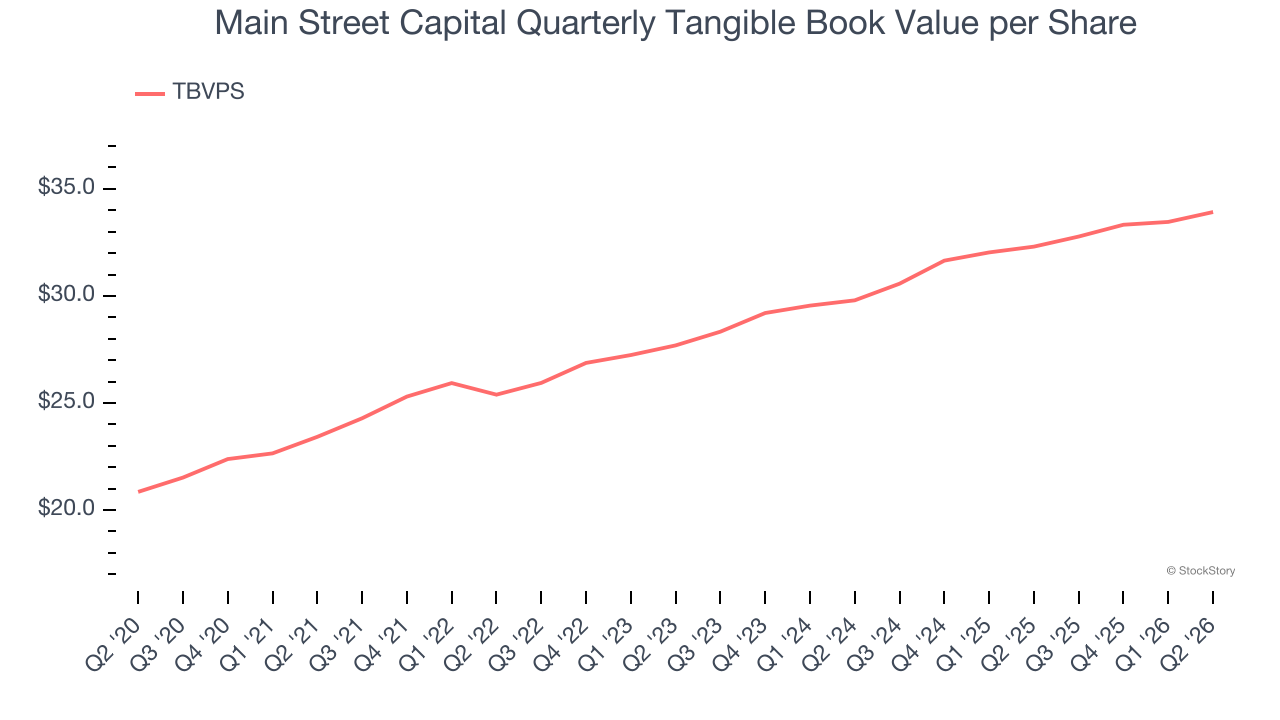
In the financials industry, tangible book value per share (TBVPS) provides the clearest picture of shareholder value, as it focuses on concrete assets while excluding intangible items that may not hold value during challenging times.
To the detriment of investors, Main Street Capital’s TBVPS grew at a mediocre 6.7% annual clip over the last two years.
Final Judgment
Main Street Capital isn’t a terrible business, but it doesn’t pass our quality test. With its shares lagging the market recently, the stock trades at 14.5× forward P/E (or $55.26 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.